Homeowner Shocked to Discover a $4,000 Deductible After Storm Damages His Roof
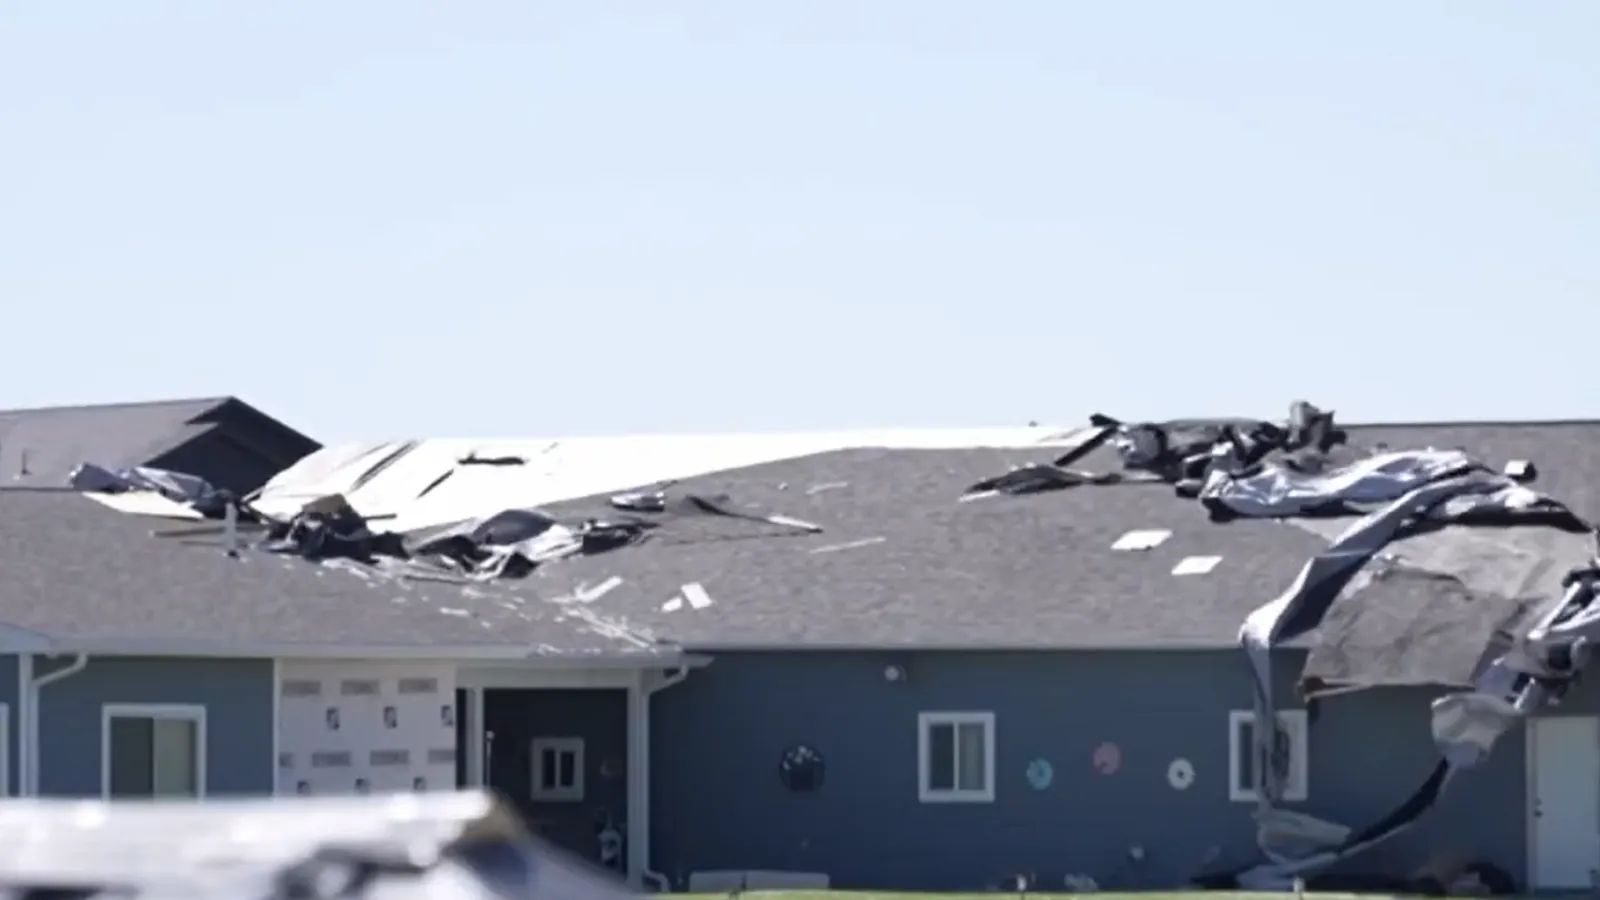
A fallen tree left one Ohio homeowner with roof damage to repair. That was only the beginning of the unpleasant surprises. Next came another unwelcome discovery: the insurance deductible he remembered as $1,000 had quadrupled.
Carl Roberts learned he would be responsible for the first $4,000 in repairs, according to WCPO 9. Roberts said his deductible had changed from a flat $1,000 to an amount equal to 1% of his home’s value.
“That’s a pretty significant deductible,” Roberts said. “My spouse and I were a little shocked when we found that out.”
Percentage Deductibles Can Add Up Quickly
Embedded media follows. Please allow a moment for it to load.
A deductible is the portion of a covered loss a homeowner must absorb before an insurance company begins paying its share. While many people may be accustomed to seeing a fixed amount such as $500 or $1,000, deductibles can also be calculated as a percentage of a home’s insured value.
The National Association of Insurance Commissioners notes that percentage deductibles are used in homeowners insurance and adds that some policies have separate deductibles specifically for wind or hail damage.
One percent can sound small on paper. Once it’s attached to the value of a house, however, it can quickly and easily represent thousands of dollars.
That became especially important for Roberts because his actual repairs never reached the deductible. He eventually found a contractor who could repair the roof and gutter for less than $2,000, WCPO reported.
Because the repair cost remained below his $4,000 deductible, Roberts paid the entire bill himself.
Homeowners May Want to Check Before the Next Storm
The insurance industry is also dealing with increasingly expensive claims.
The 2026 LexisNexis U.S. Home Insurance Trends Report found that the average severity of home insurance claims reached a seven-year high in 2025. LexisNexis pointed to both catastrophic weather and rising repair and replacement costs as pressures on the industry.
The NAIC urges homeowners to review homeowners coverage periodically and make sure a deductible is affordable before a loss occurs.
Insurance paperwork is easy to ignore when the roof is intact, and the trees are still standing. Roberts’ experience shows why the number buried in that policy can become very real the moment a storm arrives.